

Key Takeaways
- The best coastal home supports the way you expect to live, not simply the lifestyle shown in listing photos.
- Location, insurance, taxes, association dues, maintenance, and rental rules all affect the real cost of ownership.
- Flood exposure, drainage, elevation, and storm readiness deserve careful review before an offer is made.
- Condos, townhomes, and detached homes can deliver very different levels of privacy, upkeep, and flexibility.
- A simple comparison process can help buyers make a confident decision when several homes seem appealing.
Start With The Life The Home Needs To Support
A Hilton Head Island home should work during an ordinary week, not only during a perfect vacation. Before choosing a neighborhood or property type, ask, “How will this home be used during an average week?” A full-time resident may prioritize grocery access, medical services, bike paths, and a manageable commute. A second-home owner may value lock-and-leave convenience. Retirees may want a one-level layout, while families may need storage, flexible bedrooms, and room for visiting guests.
When comparing homes for sale in Hilton Head Island, SC buyers can use John Campbell’s local property-search resource to see different home styles, locations, and price ranges in one place. John Campbell provides local real estate guidance for buyers exploring Hilton Head Island and nearby Bluffton, making the resource especially useful for understanding how island communities, coastal property types, and buyer priorities can differ from one area to the next.
Compare Areas By Their Daily Rhythm
Hilton Head Island offers distinct daily experiences. Some buyers want quick beach access and lively seasonal activity. Others prefer golf-oriented communities, marina settings, wooded streets, or a location closer to year-round services. None is automatically better for potential homebuyers. The right fit depends on how much activity, privacy, driving, and maintenance you want.
Visit a preferred area more than once, ideally at different times of day and in different conditions. A quiet weekday morning can feel very different from a busy weekend afternoon. As you tour, look beyond the house itself and consider:
- Distance to the places you will visit most often.
- Road access and traffic during peak visitor periods.
- Nearby grocery stores, dining, health care, and other services.
- Bike paths, walking routes, and parking options.
- Privacy, views, shade, and usable outdoor space.
Choose A Property Type That Matches Your Priorities
Property type shapes both your routine and your budget. A lower purchase price does not always mean lower monthly ownership costs, particularly when association dues, insurance, repairs, and amenities are considered.
- Condos: These can work well for buyers who want shared amenities and less responsibility for exterior maintenance. Review the association’s financial health and understand exactly what dues cover.
- Townhomes: A townhome may offer more living space and a more house-like layout while still shifting some exterior tasks to an association. Shared walls, parking rules, and outdoor-use restrictions should be part of the decision.
- Single-family homes: Detached homes often provide more privacy, storage, yard space, and freedom to personalize outdoor areas. They can also require more hands-on planning for landscaping, roof care, pest control, and storm preparation.
Build A Realistic Ownership Budget
Start with the mortgage payment, then build outward. A complete ownership budget should include property taxes, homeowner’s insurance, possible flood insurance, HOA or regime dues, utilities, routine maintenance, landscaping, pest control, and a reserve for repairs. If rental use is part of the plan, add management, cleaning, furnishing, marketing, and turnover expenses.
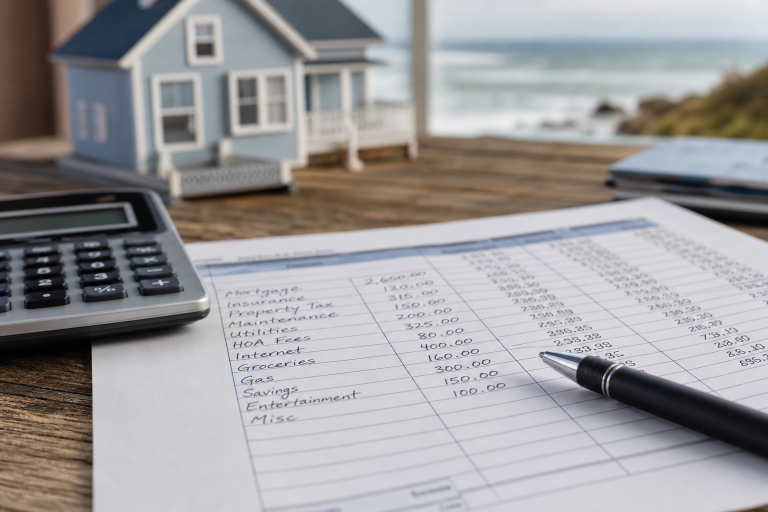
Ask for insurance estimates before submitting an offer, rather than treating them as an afterthought. Review HOA budgets, reserve balances, recent meeting minutes, pending projects, amenity fees, and any history of special assessments. Set aside a repair reserve for larger items such as roofs, HVAC equipment, windows, decks, exterior finishes, and drainage improvements. Closing costs and applicable local fees should also be part of the cash-to-close calculation.
Treat Flood And Storm Research As Standard Due Diligence
Flood zone, storm-surge exposure, elevation, drainage, and insurance are related but separate questions. A listing description cannot replace property-specific research. Buyers should check the flood designation, request an elevation certificate when one is available, ask about past water intrusion and drainage issues, and examine the age and condition of the roof, windows, doors, and exterior materials.
Standard homeowners insurance generally does not cover flood damage, so separate coverage may be relevant even when a property is not in the highest-risk designation. The Town’s flood insurance guidance for property owners is a helpful starting point for understanding the questions to raise with an insurance professional. A thorough inspection and a direct discussion with the seller can provide useful context about how the property has performed in heavy rain and prior storms.
Review HOA Rules And Rental Limits Carefully
Association documents deserve the same attention as the home’s floor plan. Read the covenants, rules, budgets, insurance provisions, and recent meeting minutes. Confirm pet policies, parking limits, renovation approval requirements, exterior-maintenance duties, and restrictions affecting boats, golf carts, signage, or storage.
Buyers considering short-term rental income should confirm both community restrictions and local requirements before relying on projected revenue. Rental minimums, occupancy limits, registration rules, and management expectations can change the financial picture significantly. If meeting minutes point to planned repairs, litigation, insurance concerns, or rising dues, factor those issues into the offer and long-term budget.
Think About Resale Strength And Future Flexibility
A home can serve different roles over time. It may begin as a vacation home, become a retirement base, accommodate extended family, or eventually be sold to another lifestyle buyer. Features with broad appeal often include a practical layout, usable outdoor living areas, adequate parking, storage, low-maintenance finishes, and easy access to the amenities that matter in that part of the island.
Keep personal taste in perspective. A highly customized feature may be perfect for you, but less important to a future buyer. Also review nearby development, road work, community improvements, and any changes that could affect traffic, views, access, or the overall feel of the area.
Use A Simple Home-Comparison Scorecard
After several tours, it is easy to remember the view and forget the trade-offs. Score each finalist from one to five in the following categories, then write a brief note explaining each score:
- Location: Does the area fit your actual daily routine?
- Total cost: Are taxes, insurance, dues, and maintenance comfortable within your budget?
- Condition: Are major repairs likely in the near future?
- Risk: Have flood, storm, drainage, and elevation concerns been reviewed?
- Flexibility: Would the home still work if your plans changed?
- Resale: Does it offer practical features that may appeal to future buyers?
Follow A Clear Pre-Offer Process
- Set a total monthly ownership budget, not just a target purchase price.
- Identify your preferred lifestyle and property type.
- Compare at least three neighborhoods or communities.
- Request insurance estimates and association documents.
- Review flood, elevation, drainage, and storm-related information.
- Schedule a detailed inspection.
- Estimate immediate repairs and ongoing maintenance.
- Make an offer based on the full ownership picture.
Common Questions Buyers Ask
Is A Condo Or A Single-Family Home Better For A Second Home?
Condos can suit buyers who want simpler exterior upkeep and shared amenities. Single-family homes may offer more privacy, outdoor space, and control. The better choice depends on your budget, rental plans, desired maintenance level, and how often you expect to use the property.
What Costs Should Buyers Review Before Making An Offer?
Review the mortgage, property taxes, homeowner’s and flood insurance, association dues, utilities, repairs, landscaping, pest control, and possible rental-management expenses. Ask for documentation whenever possible instead of relying on broad estimates.
Should Buyers Worry About Flood Risk Outside A High-Risk Zone?
Yes. A lower-risk designation does not mean zero risk. Review elevation, drainage, property history, proximity to water, insurance options, and the home’s storm-readiness features before deciding.
How Many Homes Should A Buyer Tour?
Tour enough homes to understand the trade-offs. For many buyers, three to six well-chosen properties reveal which priorities are truly nonnegotiable. The quality of comparison matters more than reaching a fixed number.
Make The Decision With Both Today And Tomorrow In Mind
The right Hilton Head Island home is one that fits present needs while leaving room for future plans. By comparing location, property type, complete ownership costs, storm exposure, HOA rules, and resale flexibility, buyers can move beyond the initial emotional pull of a listing and make a more durable long-term decision.


